
New Jersey Might Owe You Property-Tax Relief. November 2 Is Not a Suggestion.
Senior homeowners must apply; the state will not automatically file PAS-1 for them. Plus: Stay NJ changed, Social Security is exempt in NJ, and one extra withdrawal can change your pension exclusion.
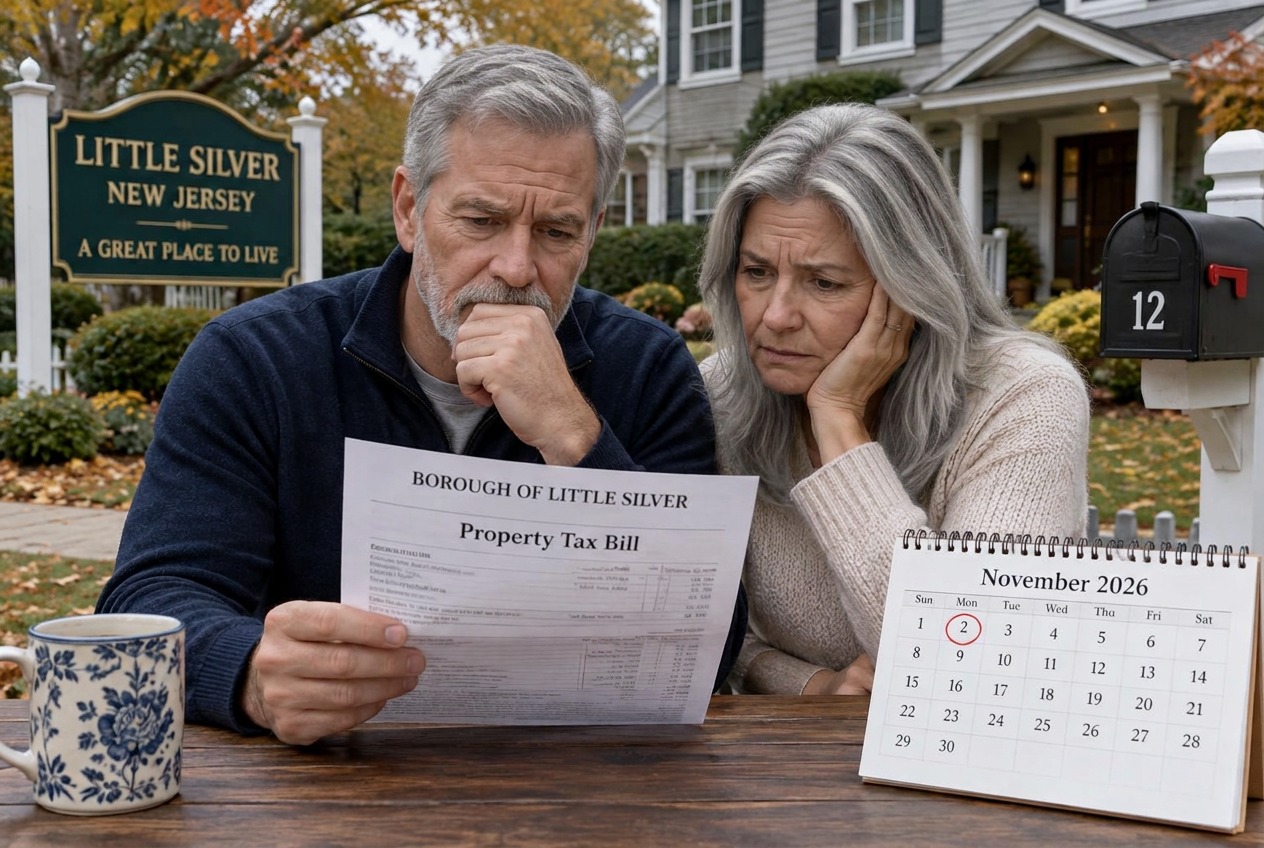
New Jersey has found a way to make retirement property-tax relief sound like an airport departure board.
ANCHOR. Senior Freeze. Stay NJ. PAS-1.
Four labels. One very practical question: have you actually applied?
The confirmed deadline for the 2025 property-tax-relief application is Monday, November 2, 2026. The Division of Taxation states it directly. This is not a date we guessed because a weekend moved something. [1]
For senior homeowners, “they already have my information” is not a filing strategy.
Checked October 11, 2026. The application is filed in 2026 for 2025 benefits. Some Stay NJ payments occur in 2027. Benefit eligibility and funding depend on current state rules and budget appropriations; maximums are not guaranteed individual payments.
Cover: AI-created editorial illustration. The retired couple, giant mailbox and accountant gnome are fictional; the glow is not a promise of a check.
The Calendar: Two Different Deadlines, Two Different Jobs
- Thursday, October 15, 2026: the ordinary extended filing deadline for a 2025 NJ income-tax return if you have a valid extension. New Jersey requires at least 80% of the tax liability to have been paid by April 15, 2026 for the extension to be accepted. That requirement does not mean the unpaid balance is interest-free. [2]
- Monday, November 2, 2026: the 2025 property-tax-relief application deadline. A tax-return extension does not replace this application. [1]
- Before December 31, 2026: review how additional 2026 taxable withdrawals, gains or a proposed Roth conversion would affect your NJ retirement-income exclusion. This is a planning checkpoint, not the PAS-1 deadline.
If you remember only one distinction: filing your income-tax return and applying for property-tax relief are not the same task.
Senior Homeowners: You Must File PAS-1 Yourself
NJ’s current instructions say senior homeowners and qualifying Social Security Disability or Railroad Retirement Disability benefit recipients must complete the combined Application for Property Tax Relief, Form PAS-1. The state will not automatically file it on their behalf. That applies even if they do not qualify for all three programs. File online or use the paper application. [1]
Do not skip the application because Stay NJ does not fit your circumstances. ANCHOR or Senior Freeze may be a different story.
Also, “I do not have to file an income-tax return” does not automatically mean “I cannot apply for property-tax relief.” The state’s FAQ explicitly allows relief applications from people not required to file an income-tax return. [3]
Start at the official NJ property-tax-relief page. It links to filing, forms and benefit-status checks. The online route requires identity verification through ID.me; prepare your identification before the deadline week.
Renters and Under-65 Homeowners: The Automatic-Filing Rule Is Different
The state automatically filed ANCHOR applications for most eligible homeowners under 65 who are not receiving the specified disability benefits, and for most eligible renters of all ages. That is not the same rule as the senior-homeowner PAS-1 requirement.
Qualifying residents were sent ANCHOR Benefit Confirmation Letters on August 10, 2026. The change deadline was September 15 — already past as of this article. If you did not receive a confirmation letter, the official page says you may file on your own by November 2, 2026. [1]
Check your actual filing status. Do not borrow your neighbor’s answer; your age, housing and disability status may send you down a different lane.
Stay NJ Changed. The Old Headline Is Not Your Benefit Statement.
This is the important new-law wrinkle.
The Fiscal Year 2027 Appropriations Act, signed June 30, 2026, changed the program. For the 2025 tax-year application and 2027 program, NJ now lists a Stay NJ income ceiling of $200,000. [4]
To qualify, you or your spouse must have been 65 or older during 2025, owned and lived in the home for the full 12 months of 2025, and lived in a property subject to property taxes or qualifying P.I.L.O.T. payments. Renters and mobile-home owners are not eligible for Stay NJ.
The current page lists these annualized maximums:
- Income $0–$100,000: $6,500.
- $100,000.01–$150,000: $5,000.
- $150,000.01–$200,000: $4,000.
- Over $200,000: no Stay NJ benefit under the listed rule.
Read the asterisk before spending the money. NJ says those maximums assume no changes in the Fiscal Year 2028 budget. They are not an unconditional annual check, and your statement determines your actual benefit.
The current page schedules the 2025 benefit for February and May 2027. It separately says the remaining 2024 benefit is paid in August and November 2026, and that budget changes lowered the overall 2026 benefit. Different benefit years, different payment dates. [4]
The state issues a benefit statement showing Senior Freeze, ANCHOR and Stay NJ amounts. Do not add every advertised maximum together and build your budget around the total.
Senior Freeze Does Not Mean the Town Stops Raising Your Bill
Senior Freeze is a property-tax reimbursement program. The name does not mean the local tax bill is frozen in place.
For the current application, NJ lists an age/disability test, home-ownership requirements and income limits for both relevant years. The published limits are $168,268 for 2024 and $172,475 for 2025, with combined income rules for married/civil-union couples living together. [5]
The page says homeowners generally must have owned and lived in the home since December 31, 2022 or earlier and still done so on December 31, 2025. Mobile-home site-fee rules and special situations require their own check.
Eligibility and benefits remain subject to state-budget appropriation. Use the current checklist, not a friend’s old application.
Good News: NJ Does Not Tax Social Security. Different News: Washington Can.
New Jersey excludes Social Security and Railroad Retirement benefits from its income tax. That does not automatically make pension income, annuities or IRA withdrawals tax-free. [6]
And the federal rules are separate. Our federal companion explains the new senior deduction — and why it did not repeal Social Security taxation.
Also separate: a program’s application-income definition. Do not assume income omitted from an NJ income-tax return is automatically omitted from every property-tax-relief calculation. Follow the current application’s instructions.
The Pension Exclusion Has a $125,000 Band. Yes, It Matters.
NJ’s existing pension exclusion can shelter some taxable pension, annuity and IRA income. Generally, you or your spouse must be 62 or older, or meet the disability test, at year-end, and total income must be $150,000 or less. If only one spouse qualifies, only that spouse’s qualifying retirement income can be excluded. [7]
For total income of $100,000 or less, the maximum pension exclusion is the lesser of eligible taxable retirement income or $100,000 for joint filers, $75,000 for single/head-of-household/qualifying-survivor filers, or $50,000 for married/civil-union separate filers.
Above $100,000, the rule switches to a percentage of reported taxable pension, annuity and IRA income:
- $100,001–$125,000 total income: 50% for joint filers; 37.5% for single/head-of-household/qualifying-survivor filers; 25% for separate filers.
- $125,001–$150,000: 25% for joint filers; 18.75% for single/head-of-household/qualifying-survivor filers; 12.5% for separate filers.
- Over $150,000: no pension exclusion.
These percentages apply to the qualifying taxable retirement income — not to every dollar of household income. NJ also has an Other Retirement Income Exclusion worksheet with additional conditions; it is not an automatic extra allowance.
Illustration using the published joint-filer bands: with $60,000 of qualifying taxable pension income, total income of $125,000 permits a $30,000 pension exclusion. Total income of $125,001 falls into the next band, producing a $15,000 exclusion on that same $60,000. That is an exclusion calculation, not your final tax bill, and assumes the other requirements are met.
One extra dollar of income can change the exclusion by much more than one dollar. Before a large withdrawal, gain or conversion, ask your preparer to model the state result as well as the federal one. Verify the current tax-year return instructions before filing.
Your IRA May Have a Different NJ Tax History
New Jersey’s pension and annuity guide explains that traditional IRA contributions generally were taxed by the state when made, so those contributions are not taxed again when withdrawn. Earnings and amounts rolled from other plans can have different treatment. [8]
That means the federal taxable amount is not automatically the NJ taxable amount. Bring contribution and rollover records to your preparer. Guessing that the entire withdrawal is taxable — or that none of it is — can both be wrong.
Your This-Week Checklist
- Finish any validly extended 2025 NJ income-tax return for October 15.
- Check whether the state filed your ANCHOR application or whether you must submit PAS-1 yourself.
- Apply through the official route by November 2, 2026; keep submission confirmation or mailing records.
- Review eligibility using 2025 facts and the current program rules.
- Before adding 2026 income, ask what it does to the NJ pension exclusion and other income-sensitive benefits.
The most useful retirement tax break is the one you qualify for and actually claim.
Use the official NJ filing and benefit-status page for the application, and read the federal tax-deadline companion for the other half of the picture.
For your bigger retirement-income plan, join our Retirement Webinar: Setting the Stage for 2027.
Sources: [1] NJ property-tax-relief overview. [2] NJ income-tax extensions. [3] NJ property-tax-relief FAQ. [4] Stay NJ current program page. [5] Senior Freeze eligibility. [6] NJ pension and annuity income. [7] NJ retirement-income exclusions. [8] NJ GIT-1&2 pension and annuity guide. All are official NJ Division of Taxation sources, linked beside the relevant passages and checked October 11, 2026.
General education, not individualized tax, investment or legal advice. Program funding, eligibility rules and deadlines can change. Consult a qualified tax professional and current official application instructions for your situation.
Share a line
Pass this one along
Pick a line, save the card, and send it to whoever needs to read it.
Your next step
Questions about your own retirement?
Talk it through with a licensed advisor on our team. Ask your questions, get straight answers, and leave with a clear place to start. No cost, no obligation, nothing sold on the call.
Run your own numbers
The Let’s Start tool
Prefer to try it yourself first? It’s a calculator that sets a retirement income target and shows how much savings could support it.
Open the Let’s Start →Advisory and insurance services are provided by licensed professionals; availability varies by state.
The Conversation
No comments yet. Tell us where we got it right — or where we're dead wrong.
Comments are for members — it keeps the spam out and the conversation honest.
Create a free account