
Section
Retirement
Money, timing, and the life after work
Your IRA Has a Silent Partner. Guess Who Gets Paid When You Retire?
The balance is yours to manage. The entire balance may not be yours to spend. Here’s how taxes change the retirement paycheck. You set the retirement table for two. There is a third place setting. Nobody invited Uncle Sam to dinner. But if much of your savings is in a traditional IRA or a pre-tax 401(k), he may already have a claim on…
Your Retirement Paycheck Didn’t Shrink. Your Life Did.
Same deposit. Smaller grocery haul. Inflation can quietly turn a comfortable retirement into a string of compromises. The money hits your account on time. Same amount as last month. Same amount as last year. So why are you putting the nice olive oil back on the shelf? Inflation rarely announces itself as a retirement emergency. It…
Your Retirement Can Survive a Bad Market. A Bad Beginning Is Another Story.
The market’s average return is not your retirement paycheck. The order of the rough years can matter more than you think. You packed for a twenty-year hike. Good boots. Plenty of supplies. A route that looks perfectly reasonable on paper. Then the first mile turns into a mudslide. That is the retirement problem an average-return…
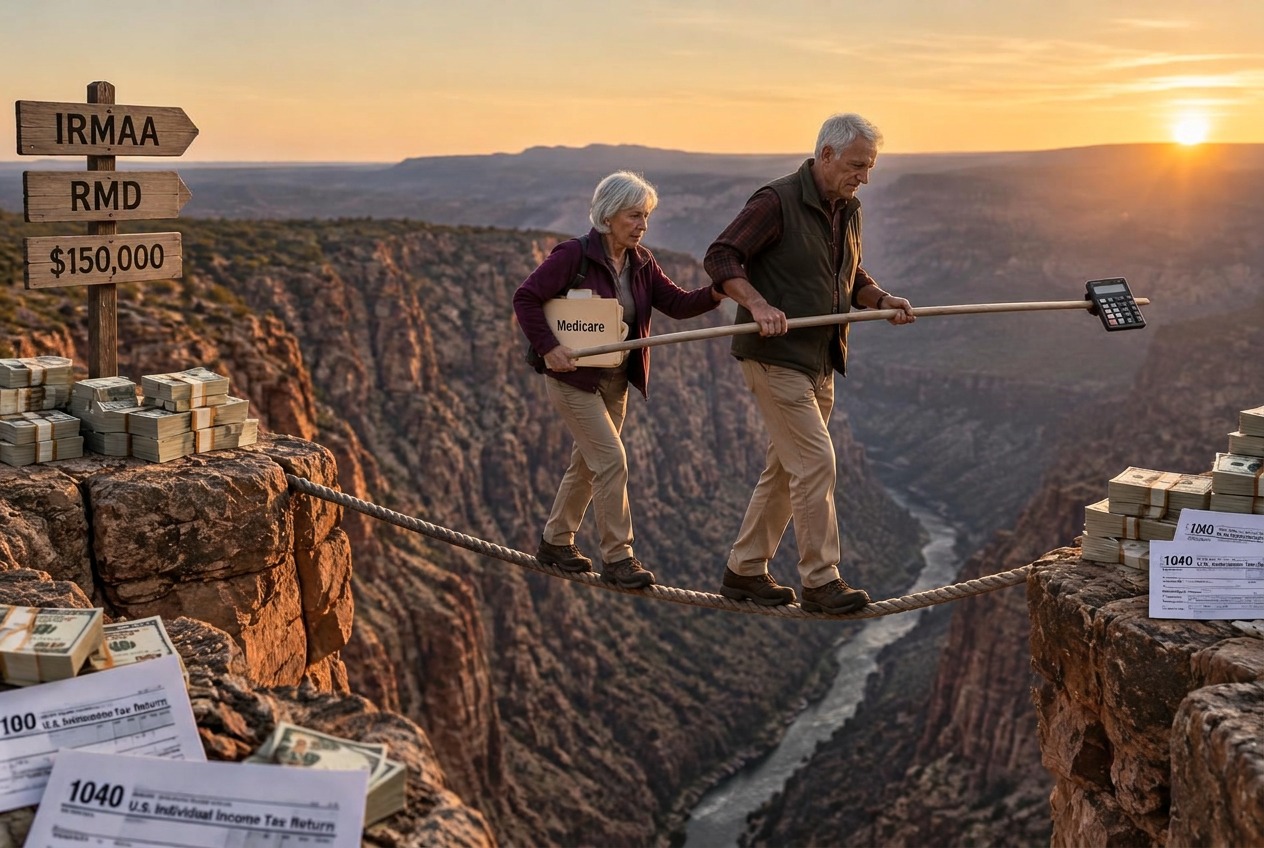
One Dollar Over the Line: The Income Cliffs That Can Cost Retirees Thousands
In retirement, your income is a number you largely choose — and three government programs draw lines across it. Step one dollar over the wrong line and it can cost you thousands. Here are the cliffs, in plain English, and the moves that keep you on the right side. Here is something nobody tells you when you retire: your income is no…
New Jersey Might Owe You Property-Tax Relief. November 2 Is Not a Suggestion.
Senior homeowners must apply; the state will not automatically file PAS-1 for them. Plus: Stay NJ changed, Social Security is exempt in NJ, and one extra withdrawal can change your pension exclusion. New Jersey has found a way to make retirement property-tax relief sound like an airport departure board. ANCHOR. Senior Freeze. Stay NJ…
Uncle Sam Does Not Retire: The Tax Breaks and Deadlines to Check Now.
The $6,000 senior deduction is real. A $6,000 refund is not promised. Here is what changed, what did not, and which dates belong on your retirement calendar. Retirement is supposed to come with fewer meetings. Apparently, nobody told the tax code. There is a new senior deduction, an old Social Security tax calculation that did not…
Weekly Market Update — October 5–9: 5.24% Isn't Your Spending Budget
Stocks rose and Treasury income looks tempting. Neither gives your retirement spending plan permission to start acting like it won the lottery. The Week in Your Money is our weekly market read for people living off — or about to live off — their savings. Numbers through the close on 2026-10-09. The 10-Year Treasury yield—the annual…
Your Retirement Plan Might Be Fantasyland. Here Are 7 Missing Pieces.
The castle is lovely. The moat is not a cash reserve. Before you retire on a beautiful projection, check the seven pieces that turn a dream into a plan. You have the retirement date. The travel list. The house with the good view. Maybe even a spreadsheet that stays reassuringly green all the way to age 95. Lovely. But if the numbers…
The Bank of Mom and Dad Needs a Closing Time.
You can love your adult children without putting your retirement on an unlimited payment plan. The hard conversation is not about generosity. It is about whether the help has an end. The first request sounded reasonable. A little help with rent. A car repair. Something to get them through a rough month. Then the rough month developed a…
You Saved for Freedom. Why Does Spending It Feel Like a Crime?
The cage door is open. The suitcase is packed. But after decades of saving, some retirees still cannot give themselves permission to leave. Here’s how to separate a real money problem from a lifetime habit. You spent decades doing the responsible thing. You skipped things. You saved things. You told yourself, “We’ll do that when we…
Your Will Is Done. Your Family Isn't.
Most estate plans are technically perfect and emotionally empty. The documents transfer money — they don't prepare people. Here's what the paperwork can't do. There''s a line from a parenting framework called Love, Limits, and Latitude that has no business being as relevant to estate planning as it is: "True love between a parent and…
Equal Isn't Always Fair: The Inheritance Conversation Nobody Wants to Have
Splitting everything three ways feels like the safe choice. Sometimes it is. Sometimes it's the match that lights the fuse. Here''s a scene that plays out in estate attorneys'' offices every week: a parent, pen hovering over the will, saying some version of "just split everything equally between the three kids. I don''t want any…
The Three Ps: A Practical Framework for Estate Planning That Actually Works
Purpose, Protection, Perspective — the checklist for the part of estate planning that happens between the documents. In the first two parts of this series we covered the problem: technically perfect plans that fail families , and the equal-versus-fair conversation everyone avoids. This final part is the practical one — a framework…
Dave Ramsey Says Take 8%. Wade Pfau Says That Math Can Wreck a Retirement.
The loudest feud in retirement planning is not really about 4% versus 8%. It is about what happens when a bad market arrives before your portfolio has time to recover. Retirement planning has its own heavyweight fight, and this one is not happening quietly. In one corner is Dave Ramsey, the blunt, enormously popular radio host who says…
Weekly Market Update — September 28 – October 2: 5.28% Is Not a Spending Plan
The Treasury yield looks tempting. Your grocery bill still doesn't care what the bond market did. Here's what matters before you touch your retirement withdrawals. The Week in Your Money is our weekly market read for people living off — or about to live off — their savings. Numbers through the close on 2026-10-02. A Bigger Yield Is Not…
Two Social Security Checks Become One. The Tax Bill Doesn't Get the Message.
When a spouse dies, the survivor keeps the larger check — and roughly a third of household income vanishes. Filing status flips to single, IRMAA thresholds halve, and the RMDs keep coming. The fix is a conversation you have years ahead. Grief comes first. The paperwork comes second. But the bill that catches most families off guard…
Claim Social Security Early and Keep Working? They Take $1 of Every $2 You Earn.
If you claim before full retirement age and keep earning, the government withholds $1 for every $2 you make over $24,480 in 2026. It is not lost forever — but almost nobody knows that part. You retired on paper in March. By July you were stocking shelves part-time at the garden center on Route 35 — mostly because your spouse kept giving…
Weekly Market Update — September 21–25: The 10-Year Pays 5.18%. Stocks Have Competition.
Stocks climbed, but a 5.18% Treasury yield is the retirement story worth your attention—and it comes with a catch if you need your money early. The Week in Your Money is our weekly market read for people living off — or about to live off — their savings. Numbers through the close on 2026-09-25. The 10-Year Treasury yield closed at…
7 Year-End Money Moves to Make Before 2027 Sneaks Up on You
The smartest year-end planning is not dramatic. It is a handful of small, boring checks that can save taxes, clean up old accounts and make next year feel less chaotic. Year-end financial planning has a funny way of showing up at the worst possible time. The calendar gets crowded, the holidays start eating weekends, and suddenly the…
The 2027 Social Security Raise Is Coming. Here's What It Actually Buys You — and What It Doesn't.
The final projection for the 2027 cost-of-living adjustment is in, and the official number lands October 14. Here's the math on your check, the Medicare premium that takes a bite out of it, and what a 3.5% raise really covers at a Central Jersey checkout line. Every October, tens of millions of retirees wait for one number. This year…
The $1 Million Myth: What That Number Actually Buys You in 2026
A million dollars sounds like the finish line. Run the arithmetic and it is a monthly paycheck — a decent one, not a fantasy. Here is the honest math, line by line. Somewhere along the way, a million dollars became the retirement finish line. Hit it and you are safe. Miss it and you are not. It is the most repeated number in personal…
Your 2027 Drug Plan Is Changing. Check These 5 Things Before December 7
The national Part D base premium is rising and a stabilization program is ending. Your actual bill depends on your plan, pharmacy and prescriptions. The most expensive sentence in Medicare may be: “My plan worked fine last year.” Prescription drug plans can change premiums, formularies, pharmacy networks and cost-sharing every January…
A Nursing Home Now Costs About $112,000 a Year. What Exactly Is Your Plan?
Medicare is not a long-term-care plan. Here is how insurance, self-funding, Medicaid and family help really fit together — before a crisis chooses for you. Most retirement plans have a number for travel, a number for taxes and a number for the roof. Then long-term care appears as one vague line called “healthcare.” That line is doing…
Weekly Market Update — September 14–18: A 5.00% Treasury Yield Isn't Free Money
Treasury income looks tempting. The catch: a bond is not a checking account, and your grocery bill doesn’t care what the Nasdaq did. The Week in Your Money is our weekly market read for people living off — or about to live off — their savings. Numbers through the close on 2026-09-18. The 10-Year Treasury yield—the yearly return implied…
Claim Social Security Early and Let the 401(k) Grow? Most Couples Have It Backwards
A 64-year-old couple ran the math both ways. Spending the retirement account first and letting Social Security grow to 70 won by a mile — but only if you are actually done working. Here is the instinct almost every couple walks in with: turn on Social Security as soon as you can, leave the 401(k) alone, let it compound. It feels…
The $1.46 Million "Magic Number" Is Mostly a Myth — Two Social Security Checks Replace a Million of It
The savings target everyone quotes counts income you are already going to collect. Subtract two average Social Security checks and the number you actually have to save gets a lot smaller. Every year a survey asks Americans how much they think they need to retire comfortably, and every year the number lands somewhere north of a million…
Enjoy It Now, Keep It Later: 7 Rules for Balancing Lifestyle and Wealth
As wealth grows, spending decisions shift from simple accumulation to preserving flexibility, supporting family goals, and making sure today’s lifestyle doesn’t crowd out tomorrow’s options. One of the ongoing conversations I’ve been having with many clients lately is how to balance enjoying your lifestyle while preserving wealth for…
The Help You Didn't Know Existed: Senior Real Estate Advocates, Move Concierges and Placement Advisors
There is a whole industry built around getting an older adult out of a big house and into the right next place. Three different kinds of specialists, three different ways they get paid, and one question you should ask every single one of them. Here is the moment almost nobody plans for. The house is paid off, the stairs have gotten…
Weekly Market Update — September 7–11: Oil Crashes the Retirement Budget
Stocks slipped, oil jumped, and cash offered real competition. Here’s what matters when your portfolio pays the bills—and what deserves the mute button. The Week in Your Money is our weekly market read for people living off — or about to live off — their savings. Numbers through the close on 2026-09-11. Crude oil finished at $100.05…
Weekly Market Update — September 7–11: What Actually Mattered
New every week: the five minutes of market news that actually touch your retirement — rates, the Fed, your 401(k), and what to ignore. The Week in Your Money is a new Second Act 360 series. Every week we cut through the noise and tell you what actually moved, what it means for someone living off — or about to live off — their savings…
You Get About 10 Quiet Years to Fix Your 401(k). Most People Spend Them Doing Nothing.
Fidelity just counted a record number of 401(k) millionaires. Almost none of them own that money outright — the IRS owns a slice, and the bill comes due at 73. The window to do something about it is roughly the decade nobody uses. Fidelity recently reported a record number of 401(k) millionaires — roughly 769,000 accounts over the…
Nobody Is Cancelling Social Security. The Math Still Says Your Check Gets Smaller.
The trust fund headline gets read two wrong ways: it is going to zero, or it is a myth. Neither is right. Here is what the trustees actually project, what happens automatically if Congress does nothing, and the three fixes that keep coming back. Every year the Social Security trustees publish a report, and every year it gets translated…
Your 5% CD Was a Gift. It Is Maturing Into Something Smaller.
The safest money in retirement has a hidden risk nobody labels: the day it matures. A $500,000 ladder built at 5% renewing near 4% quietly cuts $5,000 a year of income — and the paperwork never mentions it. For two years, cash was the easiest trade in retirement. Money market funds and CDs paid 5%, the principal never moved, and nobody…
The Rule of 25 Was Built on a 7% Market. Nobody Is Forecasting One.
Save 25 times your expenses and you're done — it's the most repeated shortcut in retirement planning. It quietly assumes a 7% to 8% portfolio. Vanguard, BlackRock and AQR are all forecasting well below that. Here is what the gap actually costs you. Save 25 times your annual expenses and you are set for retirement. That is the whole…
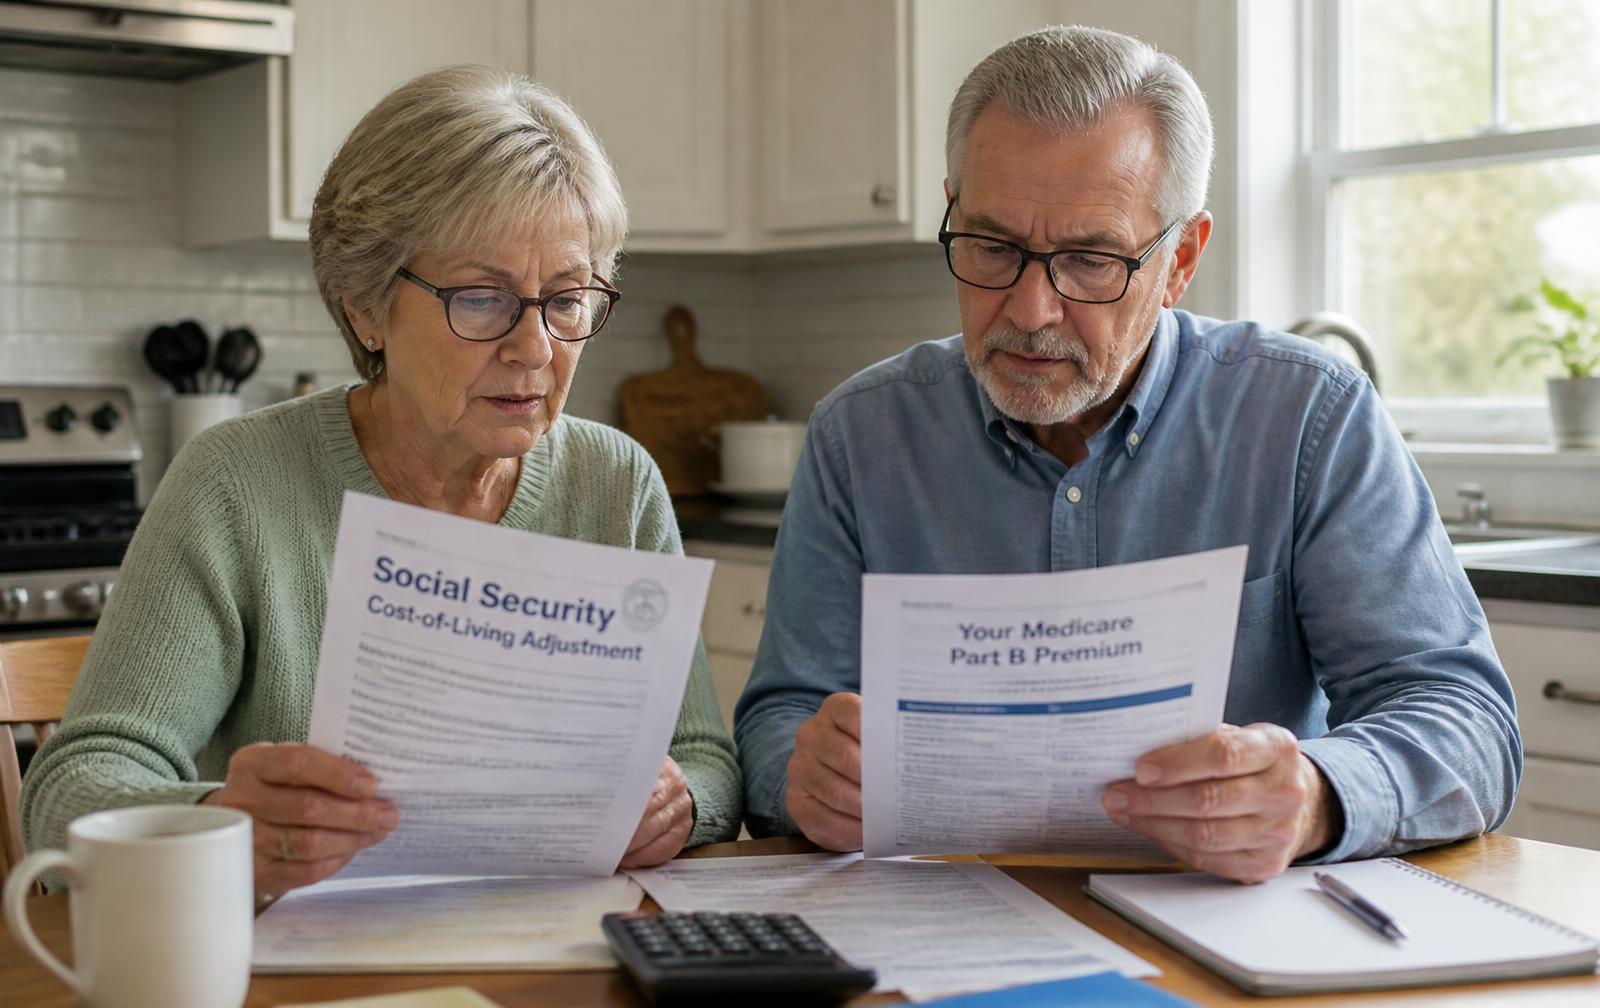
You Got a 2.8% Raise. Medicare Took a Third of It Before You Saw a Dime.
Social Security's 2026 cost-of-living bump averages about $56 a month. The Part B premium jumped $17.90. Here is the math nobody at the kitchen table wants to do — and four moves that keep the rest of your raise. Every year the same script plays out. Social Security announces a cost-of-living adjustment, the headline says seniors get a…
The 1% Fee Nobody Explains: How an Independent RIA Actually Bills Your Account
A 1% annual fee sounds small until you see it leave your account four times a year. Here’s what an independent, fee-only advisor really charges, how it’s withdrawn, and why “no commissions” changes everything. The first time you see the line item, it stings more than the brochure suggested. Your statement shows a withdrawal of $1,250 —…
Your Medicare Advantage Plan Might Not Exist in January. Insurers Are Walking.
Open enrollment runs October 15 to December 7. Insurers including UnitedHealthcare and Humana are pulling Medicare Advantage plans for 2027 — and the letter telling you so is easy to mistake for junk mail. The most expensive envelope you will get this fall looks exactly like the twelve worthless ones next to it. Medicare open enrollment…
Congress Handed 65-Year-Olds a $6,000 Deduction. Then It Took Away Your Pre-Tax Catch-Up.
Two 2026 tax changes are pulling in opposite directions: a new $6,000 deduction for people 65 and older, and a rule that forces high earners to make catch-up contributions in Roth dollars. One helps. One reshuffles your whole plan. The tax code gave with one hand this year and rearranged the furniture with the other. If you are…
Your 2027 Raise Is Already Half Spent — And Nobody Has Announced It Yet
The projected 2027 Social Security COLA is running around 3.6%. That is about $70 a month on the average check. Here is where most of it goes before it ever reaches your checking account. There is a raise coming in January. You will feel it for about one billing cycle. The Senior Citizens League, which tracks this every month, put the…
The 4 Tax Traps Waiting for You in Retirement — And Why They Gang Up on You
You did everything right: maxed the 401(k), deferred the taxes, let it grow. Nobody mentioned that deferred isn't forgiven — and that four separate tax traps are timed to arrive together. Nobody retires expecting to get mugged by their own tax return. But that is roughly what happens to a lot of people in their late 60s and early 70s…
The IRS Wrote a Withdrawal Schedule for Your 401(k). You Weren't Consulted.
Required Minimum Distributions punish the best savers hardest — and the withdrawal itself is the cheap part. It's the ripple effects that cost real money. You spent 35 years being praised for putting money into a 401(k). Nobody warned you the government wrote itself a withdrawal schedule. Required Minimum Distributions are mandatory…
You Paid In for 40 Years. Now Up to 85% of Your Check Is Taxable.
Whether Social Security gets taxed has almost nothing to do with Social Security. It's decided by every other dollar on your return — and most retirees never run that math. You paid into Social Security your entire working life. Then you get to retire and pay taxes on getting it back. Up to 85% of your benefit can land in the taxable…
The Medicare Surcharge Nobody Calls a Tax — But Your Bank Account Can't Tell the Difference
Cross an income line by one dollar and your Medicare premium jumps for a full year, triggered by a return you filed two years earlier and already forgot about. It is not called a tax. It doesn't come from the IRS. It shows up as a higher Medicare premium — and it hits because of something you did two years ago. Meet IRMAA: the…
Which Account Do You Touch First? Same Money, Wildly Different Tax Bill.
Two retirees, identical savings, identical spending — one pays far more tax over 25 years. Plus the widow's penalty almost nobody plans for. Two people retire the same year with the same $1.2 million and the same spending. One of them pays substantially more tax over the next 25 years than the other. The difference isn't returns, or…
75 Percent of the Upside, Half the Downside: How Hedged Equity Actually Works
A hedged equity strategy aims to capture about 75% of the market's gains while taking only about 50% of its losses — with tax-loss harvesting built in at the ETF level. Here is the plain-English version, and the trade-off nobody puts on the brochure. There are two ways to lose sleep in retirement. One is watching a portfolio drop 30…
A Warning Shot Over the Bow: What the Social Security Shortfall Actually Means for Your Check
The trust fund runs dry in the early 2030s. If nothing changes, benefits get trimmed by roughly a fifth — for the average household, that is real money off the kitchen table. Here is the math, minus the shouting. Every few years someone holds up a chart and says Social Security is going broke. The date on the chart keeps moving. The…
The Paycheck Problem: Why Retirement Income Is About More Than Your Net Worth
BlackRock asked 1,000 annuity owners over 60 what guaranteed income actually does for them. Their answers were not about portfolio returns. Retirement planning is obsessed with the pile. Portfolio value, account balance, net worth. But the question that actually shapes your day-to-day life in retirement is not how much you have — it is…
Your Age Is Not an Investment Strategy
"Young means aggressive, old means safe" is a bumper sticker, not a strategy. Here is what age actually tells you about your portfolio — and the four things that matter just as much. Somewhere along the way, retirement investing got reduced to a bumper sticker: young means aggressive, old means safe. It's tidy. It's memorable. And it…
Roth Conversions Are a Luxury Good. Can You Actually Afford One?
Before you lock in a 2037 conversion schedule, answer one question nobody asks: can you pay the tax bill without touching the money you need to live on? The financial media loves Roth conversions. Tax-free growth. No RMDs. Legacy planning. It sounds like a no-brainer — especially if you’re planning to start conversions in 2037 — a year…
You Built It Yourself. Who Takes Over the Day You Can't?
You beat 2000, 2008 and 2020 without an advisor. Congratulations — you are also the only risk manager your money has, and you own no life vest. Two questions worth answering before a diagnosis answers them for you. You are the investor every advisor quietly admires: the one who never needed an advisor. You lived through 2000, 2008 and…
The Boring Safe-Money Move Big Money Uses — And You Can Too
The wealthiest families in the country keep a slice of their money in something dull, guaranteed, and completely unglamorous. Here is what it is, why it beats a CD on both rate and taxes, and why the math works exactly the same on $300,000 as it does on $30 million. Almost every conversation about big money assumes the rich are doing…
Do You Know the Structure You’re Investing In?
Most people pick an investment without ever asking what structure they just entered. Here is how independent fiduciaries and broker-dealers like Guardian, LPL, and Mass Mutual actually operate differently — and why the structure shapes everything that comes next. Most people think they are buying an investment. What they are actually…
How Much Are Your 401(k) Fees? Here's How to Find Yours — and Who Made Sure You Couldn't
64% of 401(k) savers think they pay no fees. Here is the 10-minute way to find your real all-in number in dollars, what it costs you over 20 years, and the three times Congress tried to put it on your statement before the industry killed it. Part 2 of 2. Read Part 1: “My Old 401(k) Has Done Great — Why Would I Move It?” If you have ever…
“My Old 401(k) Has Done Great — Why Would I Move It?”
Three reasons nobody tells you about the old 401(k) you left behind — stacked invisible fees, a fixed menu that can't produce income, and the advisor gap that shows up the Tuesday your paycheck stops. "It's done great. Why would I move it?" That's the sentence I hear more than any other when somebody drops an old 401(k) statement on the…
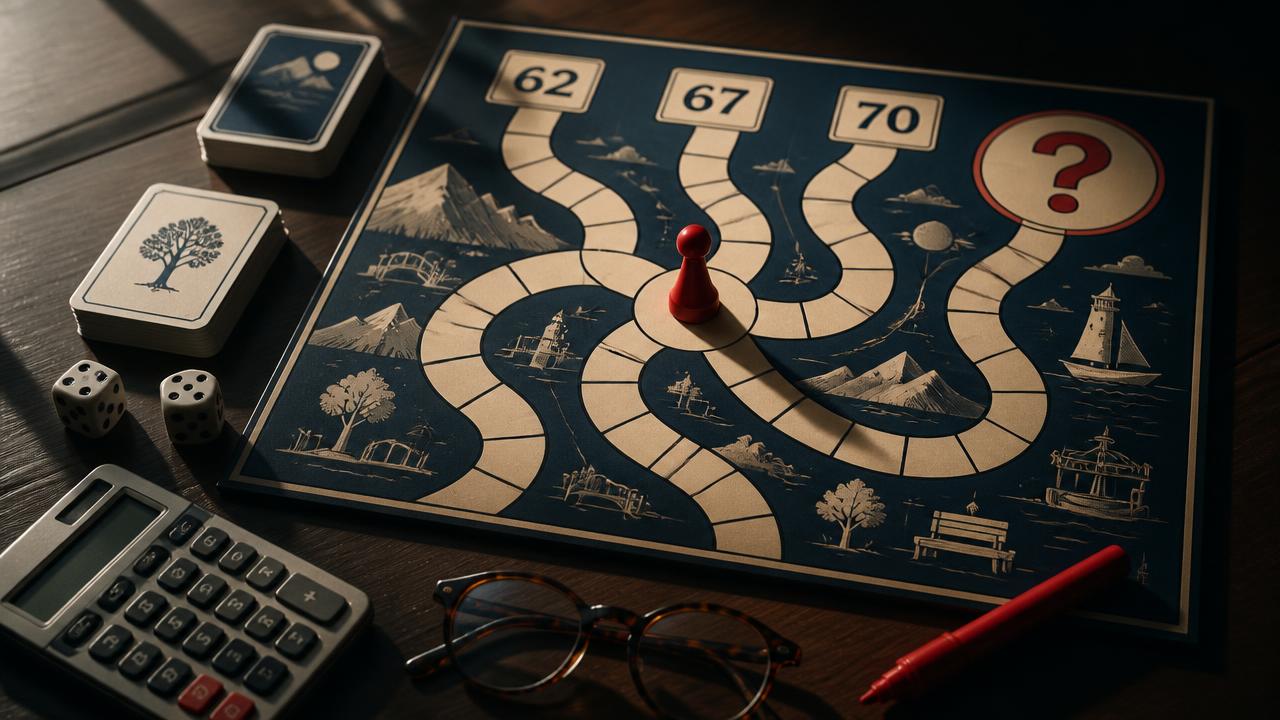
Your Social Security Statement Is Lying to You
The government assumes you'll keep working forever. The "wait until 70" rule ignores the time value of money. Here's the real math behind the biggest retirement guessing game. Everyone wants to know the "right" age to file. Age 62? 67? Wait until 70 to maximize the check? Here's the truth nobody wants to say out loud: there is no right…
The Last-Year Test: Try Retirement Before You Retire
Forget the magic number. There's a one-year dress rehearsal that tells you the truth about whether your plan actually works — and most people fail it the first time. Everybody wants a number. A single, tidy figure that means you made it — $1 million, $2 million, whatever your brother-in-law bragged about at the barbecue. Here's the…
You're Retired. Now What?
The first month feels like a vacation. The second month feels like a gap. By the third month, you realize nobody warned you about this part. retirement is not a destination. It is a complete identity renovation. You spent decades answering to alarms, deadlines, and a calendar that somebody else owned. Then one day the calendar goes…
"Your 401(k) Is a Tax Trap." Really?
A pitch is convincing thousands of retirees to drain their 401(k) into a life insurance policy they do not understand. Here is what the illustration does not tell you. Somebody slides a printout across the table. Or a YouTube link. Or a clip from Instagram. And then the question: "My friend's advisor told him the 401(k) is a tax trap…
The 12-Year IRS Timeout Almost Nobody Talks About
How a little-known IRS-approved contract can delay your RMDs from 73 all the way to 85 — and create guaranteed income for life. Here's a question I ask every client who's within five years of turning 73: "What if you could tell the IRS you'll get to your Required Minimum Distributions when you're good and ready — say, in 12 years?" The…
The 3 Retirement Myths That Could Change Your Life Forever
What you were told about retirement was true for your parents. It probably isn't true for you. Here's something I hear almost every week in my office. Someone in their late 50s or early 60s sits down across from me, takes a breath, and says: "I think I've done everything right. So why does retirement still feel scary?" The honest answer…
8 Questions to Align Your Wealth, Your Family, and Your Future
Money moves faster than values. Eight uncomfortable questions to make sure your legacy plan actually matches what you believe, who you love, and the future you want to build. Align your financial decisions with what matters most to you. We live in a world where money moves faster than values. Markets swing, tax laws change, families…
Your 7-Figure IRA Is a Tax Bomb With a Timer On It
Everyone told you to stuff the IRA. Nobody told you the IRS is holding a receipt. Here's the three-decision playbook to defuse it before it takes out your retirement — and your kids. Congratulations. You built a 7-figure traditional IRA. You did the thing they told you to do — max it out, defer the tax, let it compound. Now the IRS is…
The Cheat Code For Your 7-Figure Traditional IRA
Wall Street says convert it all to Roth. That advice will torch you. Here's how to dismantle the tax bomb inside a seven-figure IRA — on purpose, in pieces, without lighting yourself on fire. If you own a seven-figure traditional IRA, you've probably heard the pitch: "Just convert as much as possible to Roth as fast as possible." Sounds…
1 in 5 Pre-Retirees Are Chickening Out. Are You One of Them?
You have the money. You have the years in. So why are you still showing up at that desk? The dirty little secret nobody at the country club wants to admit. Let's cut the crap. One in five pre-retirees with $2M+ in the bank are hitting pause on retirement. Not because they can't afford it. Because they're scared . Scared of taxes. Scared…
Five Ways to Pay Roth Conversion Taxes (Without Cracking the Nest Egg)
The IRS wants their cut when you convert. Here are the five ways smart retirees actually pay the bill — and which one keeps the most of your money working for you. Everyone loves the idea of a Roth conversion. Tax-free growth. Tax-free withdrawals. No required minimum distributions breathing down your neck at 73. It sounds like a cheat…
Protecting Your Digital Life After You're Gone
Your email, photos, subscriptions, and crypto don't disappear when you do. A practical digital legacy guide from Abrahamsen Financial Group. Today, most of modern financial and personal life lives online — email, bank and investment accounts, cloud storage, streaming services, even cryptocurrency. Yet many estate plans still focus on…
The RMD Playbook: Uncle Sam Wants His Cut — Here's How Not to Panic
At 73, the IRS stops asking politely and starts telling you to take money out of your retirement account. The trick isn't just covering the check — it's doing it without lighting your nest egg on fire. Here's a fun fact they don't put on the AARP welcome mat: the day you turn 73, the IRS becomes your uninvited financial planner. They…

Stop saying "retirement." It's making you miserable.
The word is doing all the work — and none of it is helping you. A case for burning the term and building something better. The word "retirement" started as a factory-era compromise. You worked for 45 years, then you sat down. Simple. Cruel. We kept the word. We didn't keep the deal. The average 60-year-old today has three more decades…

Forget your net worth. These three numbers matter more.
Your advisor won't tell you this because it doesn't come with a fee attached. Everyone obsesses over the portfolio number. It's the wrong obsession. Here are three numbers that will do more for the next 20 years of your life than any 401(k) balance. One. Hours you spend outside per week. Under 10 is a warning sign. Under 5 is a crisis…