
Your Retirement Can Survive a Bad Market. A Bad Beginning Is Another Story.
The market’s average return is not your retirement paycheck. The order of the rough years can matter more than you think.
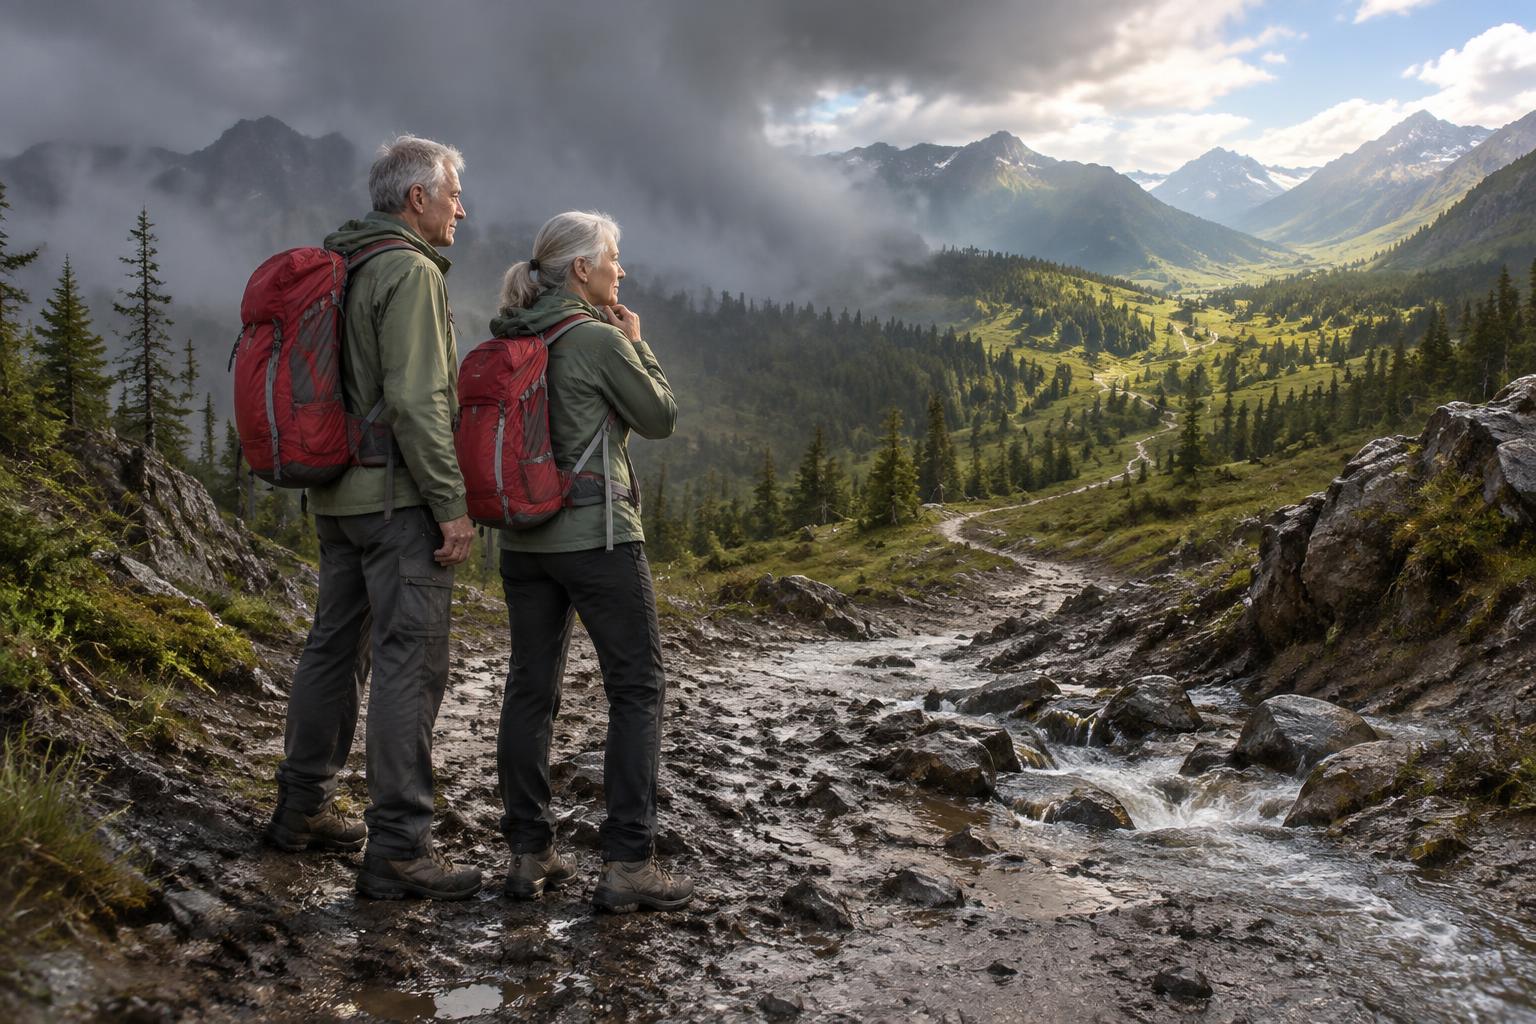
You packed for a twenty-year hike. Good boots. Plenty of supplies. A route that looks perfectly reasonable on paper.
Then the first mile turns into a mudslide.
That is the retirement problem an average-return forecast can hide. A disappointing market halfway through retirement is unpleasant. A disappointing market just as your paycheck disappears can force you to sell investments before they have a chance to recover.
Same destination. Different starting conditions. Very different trip.
Your account just changed jobs
While you were working, a downturn could mean buying investments at lower prices with your next contribution. Retirement reverses that cash flow. Now the portfolio helps pay for the kitchen, the car insurance and the life you finally have time to enjoy.
When prices fall and you still need a fixed dollar amount, you may have to sell more shares. Those shares will not be there for the rebound. This is sequence-of-returns risk: the order of investment returns matters when money is moving into or out of the portfolio. [3]
Two retirees. Same returns. A $20,000 difference.
Here is a deliberately simple illustration, not a forecast or a recommended withdrawal rate. Both people begin with $1 million and withdraw $50,000 at the start of each year. Ignore taxes, inflation and fees.
The good-start retiree: Withdraw $50,000, then gain 20%. The balance becomes $1,140,000. Withdraw another $50,000, then lose 20%. Ending balance: $872,000.
The bad-start retiree: Withdraw $50,000, then lose 20%. The balance becomes $760,000. Withdraw another $50,000, then gain 20%. Ending balance: $852,000.
Both experienced one plus-20% year and one minus-20% year. Reversing their order changed the ending balance by $20,000. Without withdrawals, either sequence would finish at $960,000.
And no, plus 20 followed by minus 20 does not get you back to even. Percentage changes apply to different balances. The lesson is not that this two-year example predicts disaster. It is that average returns alone do not describe a retirement income plan.
Build a bad-weather plan before the rain
The useful question is not “How do I avoid every down year?” Nobody can promise that. Ask instead: “What pays the bills if the market is ugly when I retire?”
Separate necessities from nice-to-haves. Housing and prescriptions need a different level of certainty than a second vacation.
Map dependable income. Social Security and pensions may cover part of the essentials. Check whether each income source adjusts for inflation.
Discuss a spending reserve. Cash or suitable short-term, high-quality holdings may reduce the need to sell stocks during a downturn. The right amount depends on your income gap, risk tolerance and portfolio; too much idle cash creates its own inflation problem.
Set spending guardrails. Decide which discretionary expenses you could trim, and when. A flexible plan beats a panicked decision made after the market falls.
Stress-test the opening years. Ask for a scenario with weak early returns, inflation and realistic taxes—not just a smooth average-growth line.
FINRA emphasizes balancing retirement risk, growth, withdrawals and inflation rather than assuming any portfolio is failsafe. [1]
The question worth taking to your advisor
“Show me where my spending money comes from if my first two retirement years are lousy.” Then ask which expenses change, which assets get sold and what would trigger a review.
A plan should not require perfect weather to get you through the first mile.
Next: why an unchanged paycheck can still shrink and what is actually yours after taxes.
Bring those questions to our Setting the Stage for 2027 Retirement Webinar.
Cover image: AI-created, realistic editorial scene illustrating the story; not a photograph of actual readers. Educational information, not individualized investment or tax advice. Numerical examples are hypothetical and exclude fees unless stated.
Share a line
Pass this one along
Pick a line, save the card, and send it to whoever needs to read it.
Your next step
Questions about your own retirement?
Talk it through with a licensed advisor on our team. Ask your questions, get straight answers, and leave with a clear place to start. No cost, no obligation, nothing sold on the call.
Run your own numbers
The Let’s Start tool
Prefer to try it yourself first? It’s a calculator that sets a retirement income target and shows how much savings could support it.
Open the Let’s Start →Advisory and insurance services are provided by licensed professionals; availability varies by state.
The Conversation
No comments yet. Tell us where we got it right — or where we're dead wrong.
Comments are for members — it keeps the spam out and the conversation honest.
Create a free account