
You Saved for Freedom. Why Does Spending It Feel Like a Crime?
The cage door is open. The suitcase is packed. But after decades of saving, some retirees still cannot give themselves permission to leave. Here’s how to separate a real money problem from a lifetime habit.
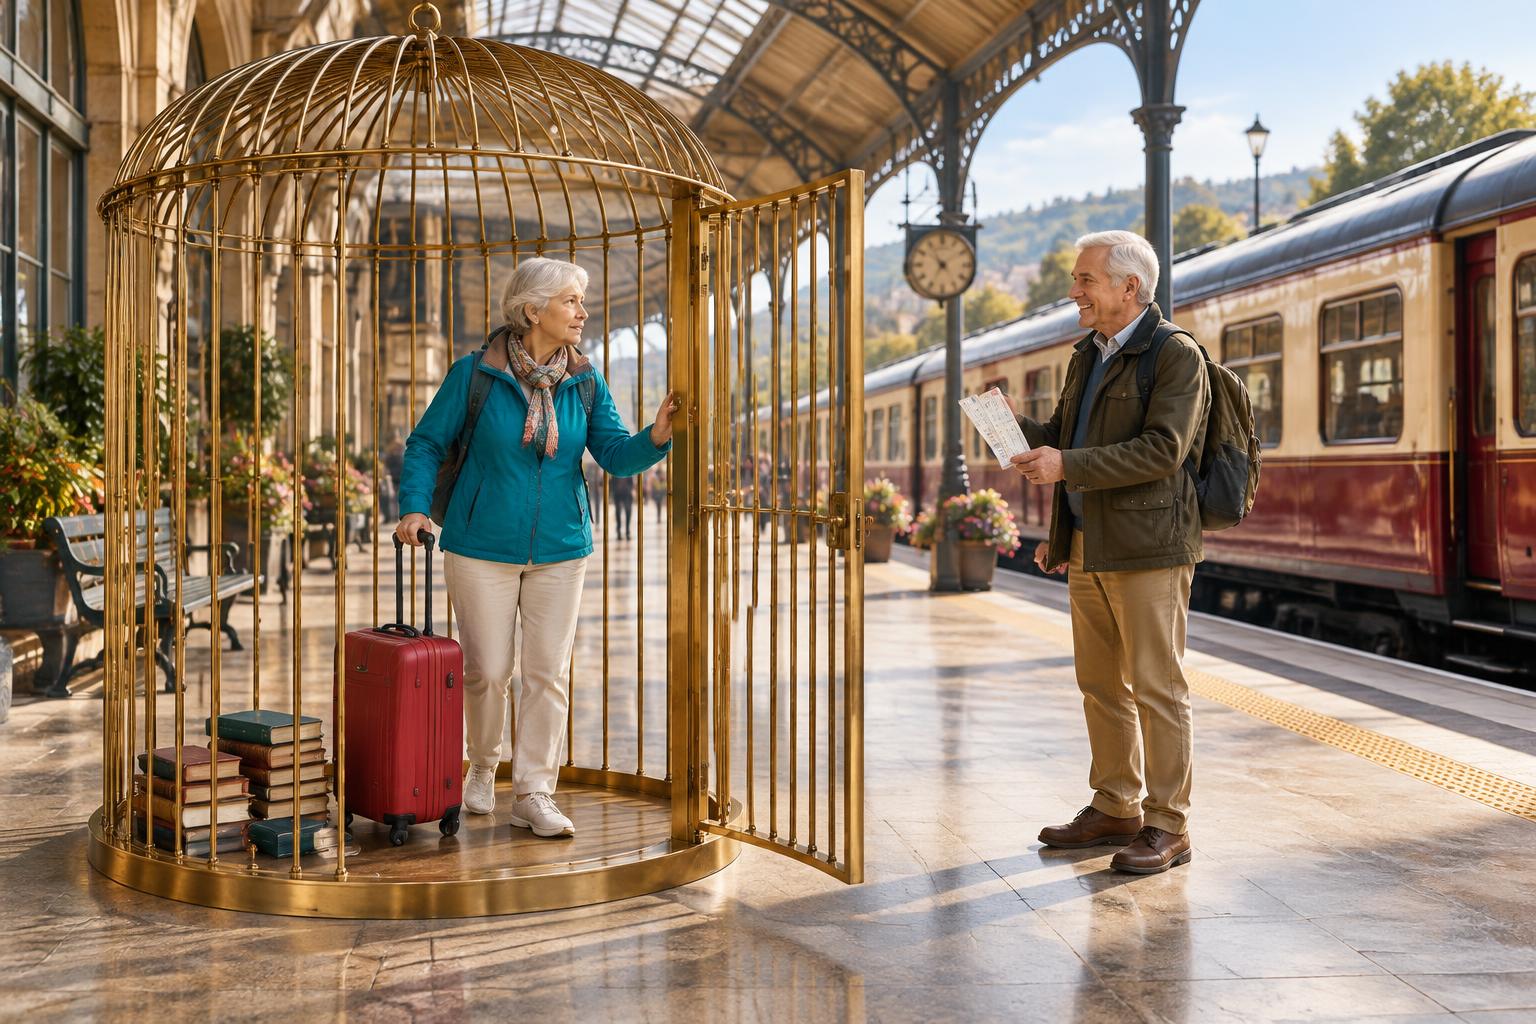
You spent decades doing the responsible thing.
You skipped things. You saved things. You told yourself, “We’ll do that when we retire.”
Now retirement is here. The trip is possible. The dinner is affordable. The money has a plan.
And somehow, buying the tickets feels like shoplifting from your own future.
You saved for freedom. Why does using it feel like a crime?
The Cage Door Can Be Open and Still Feel Locked
Here is the retirement problem nobody puts in the brochure: becoming good at accumulating money does not automatically make you comfortable using it.
A paycheck was permission. Money came in; you spent part of it. A portfolio can feel different. Every withdrawal looks like something disappearing, even when drawing from that portfolio was the whole point.
Researchers and financial planners describe this tension in work on retirement spending and “mental accounting”: people can treat income and savings differently even when both belong to the same household. A preference for leaving principal untouched can make a planned withdrawal feel like a failure. [1]
The account balance becomes the scoreboard. Life becomes the thing you keep postponing to protect it.
First: This Is Not “Spend It All” Advice
Some households do not have a guilt problem. They have an income problem, a housing problem, a care-cost problem or a savings shortfall.
They do not need someone waving a boarding pass and shouting, “You only live once.” They need a workable financial plan. The Consumer Financial Protection Bureau’s research on retirement security documents why household circumstances and financial resources matter. [2]
This story is about a different situation: when a current, realistic plan supports some enjoyment spending, but your brain vetoes every purchase anyway.
Those two situations can look identical at the restaurant table. They need very different solutions.
Stop Asking “Can We Afford It?” Without Defining “It”
“Can we afford to enjoy retirement?” is too vague to answer.
“Can we spend this amount on this trip, in this year, after allowing for taxes and the rest of our plan?” is a question someone can actually test.
Separate three things:
- What keeps the household running: housing, food, utilities, insurance, debt payments and routine healthcare.
- What protects against the unknown: appropriate reserves and a plan for longevity, inflation, market losses and possible care needs.
- What the money is also for: relationships, experiences, hobbies, comfort and the life you kept saying you would have later.
This is a thinking framework, not an instruction to buy three particular accounts or products. The right amounts depend on your household.
Give Enjoyment a Budget, Not a Blank Check
A planned enjoyment budget can be easier to live with than a series of guilty exceptions.
Decide what matters this year. Not what a luxury travel ad says should matter. What you want: the family visit, the photography class, the fishing trip, the concert seats that do not require binoculars.
Then test the actual cost against your plan.
Illustration, not a recommendation: a couple considering a $6,000 trip should evaluate the full cost, including any additional tax triggered by withdrawals, rather than assuming a $6,000 account withdrawal necessarily leaves $6,000 to spend. The result depends on where the money comes from and their tax situation.
A plan might support the trip. It might support a smaller version. It might say not this year. All three answers are more useful than indefinite guilt.
The Market Does Not Get to Cancel Your Entire Life
It is sensible to revisit discretionary spending when markets fall or circumstances change.
It is less sensible to invent a new rule every time you open your phone.
Decide in advance what would trigger a review: a meaningful change in household income, a large unexpected expense, a portfolio decline or a change in health and care needs. Have a conversation about what could be postponed and what you want to protect.
Do not confuse flexibility with panic. And do not confuse a rising market with permission to abandon the plan.
There is no universal withdrawal percentage in this article. If you want the debate behind those numbers, read our Ramsey–Pfau retirement-income showdown.
What Are You Actually Afraid Of?
“Spending makes me nervous” can hide several different worries:
- Running out of money.
- Becoming dependent on your children.
- Leaving less than you promised the family.
- Feeling irresponsible after a lifetime of being the careful one.
- Admitting that retirement is real and time is moving.
Only some of those can be solved with a spreadsheet. Name the fear before you ask the spreadsheet to fix it.
If you share finances, ask your partner what they are protecting, too. One person may be protecting future security; the other may be protecting the years when you can still travel together. Neither automatically deserves the label “reckless” or “cheap.”
Five Questions Before You Postpone Again
- Is this purchase supported by a current plan, or am I guessing?
- Have we accounted for taxes and our other commitments?
- What would make us scale it back?
- Is the hesitation about affordability, or about the feeling of watching savings decline?
- If we keep saying “next year,” what exactly are we waiting for?
You do not have to spend more to have a good retirement. Some of the best days cost almost nothing.
But if you keep denying yourself things your plan supports, ask whether protecting the balance has quietly replaced the purpose of the balance.
The goal is not to die broke. It is not to die with the largest untouched scoreboard, either. It is to make security and a life fit in the same plan.
For the broader planning conversation, join the Retirement Webinar: Setting the Stage for 2027. For family-support decisions that compete with your own plans, read The Bank of Mom and Dad Needs a Closing Time.
Sources: Journal of Financial Planning, “Right-Sizing Retirement”; CFPB research brief on retirement security and financial decision-making. This article does not claim every retiree underspends. General education, not individualized investment or tax advice. Cover: AI-created conceptual illustration, not a photograph of an actual couple or location.
Share a line
Pass this one along
Pick a line, save the card, and send it to whoever needs to read it.
Your next step
Questions about your own retirement?
Talk it through with a licensed advisor on our team. Ask your questions, get straight answers, and leave with a clear place to start. No cost, no obligation, nothing sold on the call.
Run your own numbers
The Let’s Start tool
Prefer to try it yourself first? It’s a calculator that sets a retirement income target and shows how much savings could support it.
Open the Let’s Start →Advisory and insurance services are provided by licensed professionals; availability varies by state.
The Conversation
No comments yet. Tell us where we got it right — or where we're dead wrong.
Comments are for members — it keeps the spam out and the conversation honest.
Create a free account