
The Bank of Mom and Dad Needs a Closing Time.
You can love your adult children without putting your retirement on an unlimited payment plan. The hard conversation is not about generosity. It is about whether the help has an end.
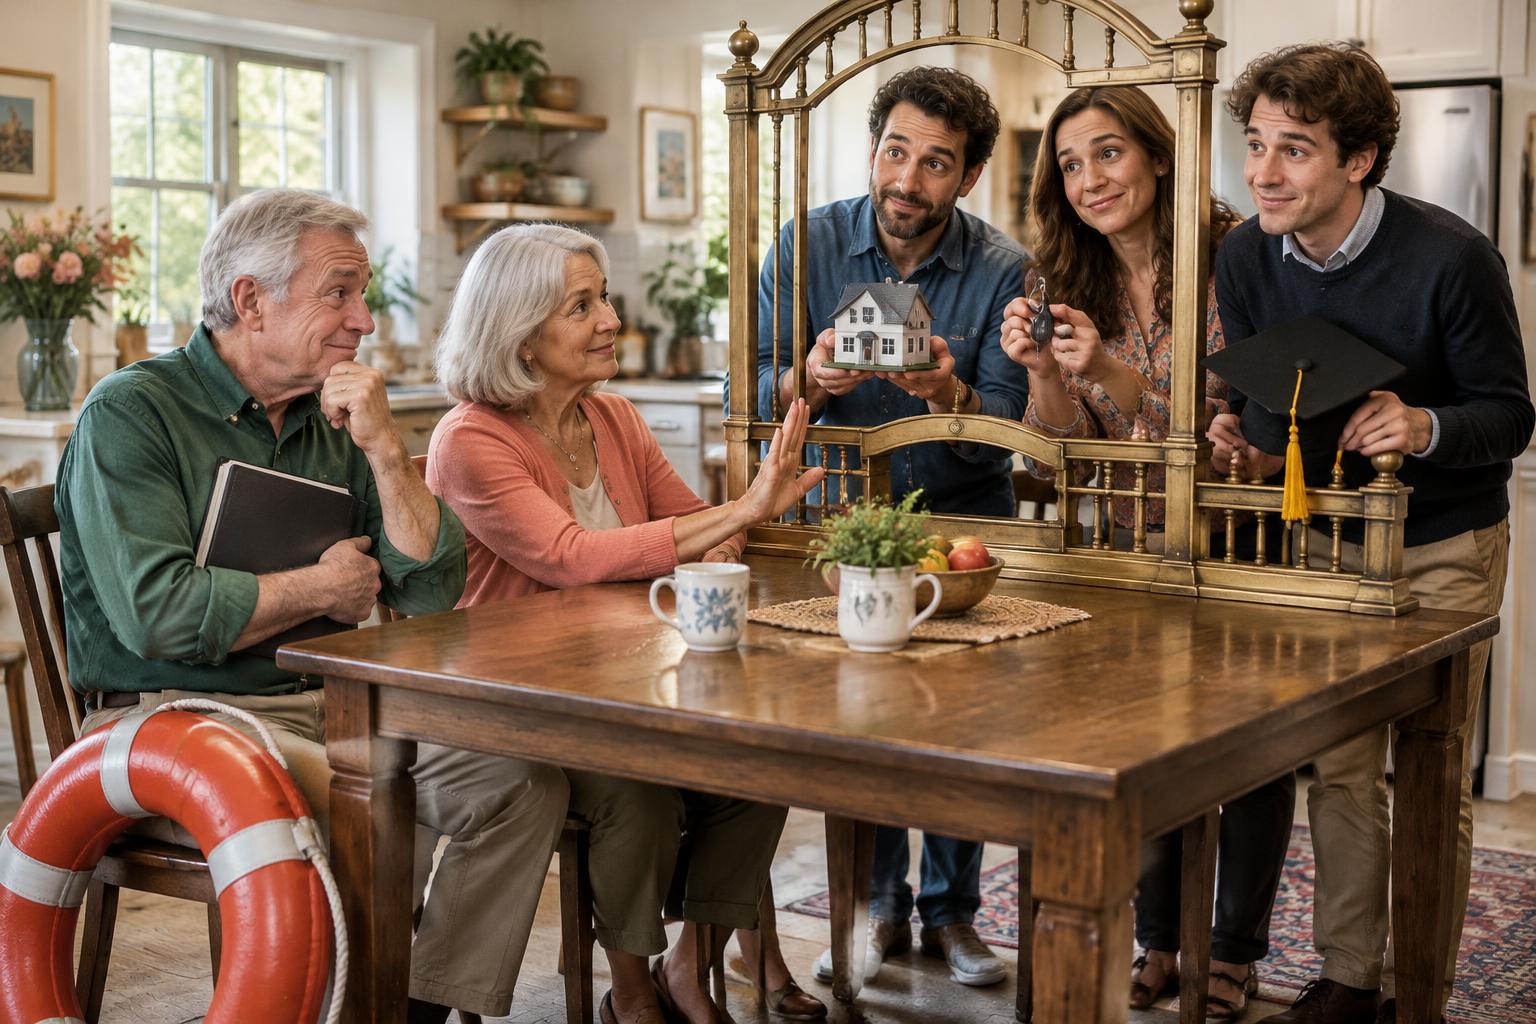
The first request sounded reasonable.
A little help with rent. A car repair. Something to get them through a rough month.
Then the rough month developed a forwarding address.
Now you are nearing retirement, still quietly paying for pieces of someone else’s adult life, and nobody has discussed when the arrangement ends.
The Bank of Mom and Dad needs a closing time.
Not because you stopped loving your children. Because love is not a retirement-income strategy.
Helping Is Not the Problem. Open-Ended Helping Is.
There are good reasons to help adult children. A medical emergency. A job loss. Disability. A difficult housing market. A genuine crisis that is not their fault.
This is not a lecture about “kids these days.” Adults with different needs require different kinds of support; a family member with a disability may need a long-term arrangement and specialized advice, not an arbitrary deadline.
But there is a difference between a deliberate family commitment and a subscription you never meant to buy.
“We can help with this” is a decision. “I guess we will keep paying” is a drift.
The Money Leaves Your Future, Not Just Your Checking Account
Regular support can become invisible precisely because it feels ordinary.
The phone bill. The insurance payment. The grocery transfer. The extra help that arrives so predictably it no longer feels extra.
Add it up.
Illustration: $500 each month is $6,000 a year. If that support continues for five years, the transfers alone total $30,000, before considering investment returns, withdrawal taxes or changes in the amount.
That does not prove the support is wrong. It makes the decision visible.
The comparison is not “my child versus a vacation.” It is the help you want to provide versus all the other things your retirement resources must cover — including a potentially long life.
Two Words That Cause Family Trouble: “Of Course”
“Of course we’ll help.”
Beautiful sentiment. Incomplete agreement.
Does help mean a one-time gift? A loan? Three months of rent? A down payment? Continued support even if your own circumstances change?
Does your spouse know? Have you told one child something you have not told the others? Are you calling it a loan because saying “gift” feels uncomfortable?
Unspoken expectations are excellent at becoming future arguments.
The Consumer Financial Protection Bureau has guidance specifically for lending to or borrowing from family and friends: discuss the arrangement and expectations rather than leaving them assumed. [1]
Give Every “Yes” Four Edges
Before you send the next transfer, define:
- The purpose. What exactly are you helping with?
- The limit. What total amount can your household afford?
- The timeframe. When does it end, or when will you formally review it?
- The conditions. Is this a gift or a loan? What happens if your situation changes?
Try this:
“We can contribute this amount toward rent through this date. After that, we need to stop because our retirement budget has to cover our own living costs. Let’s discuss the transition now.”
No courtroom speech. No character assassination. No apology for having a finite amount of money.
A Loan Is Not a Gift Wearing a Fake Mustache
If you genuinely expect repayment, discuss terms and put the agreement in writing. Consider professional help for substantial loans; interest, documentation and tax rules can matter.
Also ask the uncomfortable question: what happens to the relationship if they cannot repay?
If your plan only works because a family loan will definitely come back on schedule, that assumption deserves scrutiny before the money leaves.
And if you never intend to collect, do not build your retirement budget around a fictional future repayment.
College Has Options. Your Retirement Still Needs Funding.
Students may have access to grants, scholarships, work-study or loans, depending on eligibility. Parents should compare education costs and available options before taking on a commitment that undermines their own financial security.
That is not a promise that college aid will fill every gap. It is a reason to evaluate options instead of automatically treating parental retirement savings as the first source of funding.
The Center for Retirement Research at Boston College has examined this tension between college support and parents’ retirement. [2]
Your child’s future matters. So does the possibility that you will need those savings to live on long after the tuition bill is gone.
The Gift-Tax Rule Is Not a Generosity Budget
People sometimes hear that a gift fits within a tax exclusion and treat that as proof they can afford it.
Those are different questions.
The IRS explains that larger gifts can create reporting requirements without necessarily producing an immediate gift-tax bill. Rules for spouses, tuition, medical payments and other situations require care. [3]
“The tax rules allow it” does not mean “our retirement can sustain it.”
Ask a qualified tax professional about significant gifts or family loans. Ask your retirement plan what the commitment costs you. Do not ask either question to answer the other.
You Can Offer More Than a Transfer
Depending on the situation, help might mean reviewing expenses together, helping compare housing options, connecting them with benefits or employment resources, or contributing toward a specific one-time need instead of taking over a recurring bill.
Those options are not substitutes for necessary care. They are alternatives to assuming every problem requires another withdrawal.
When support has been ongoing, give reasonable notice where possible. A boundary announced as a surprise punishment is different from a clearly discussed transition.
The Conversation You Are Avoiding May Be the Kindest One
“We want to help without creating a situation where we later need you to rescue us.”
That is the point.
A sustainable plan lets generosity and retirement coexist. An unlimited arrangement can put both at risk.
Before your next yes, ask: Have we totaled the support? Have we agreed on it as a household? Have we tested it against our own future? Does everyone understand what happens next?
You can be a loving parent and a person with limits. In fact, your children may eventually be grateful that you were both.
Explore your own planning questions in the Retirement Webinar: Setting the Stage for 2027. For the other side of the spending conversation, read You Saved for Freedom. Why Does Spending It Feel Like a Crime? And if support now raises inheritance questions later, read Equal Isn’t Always Fair.
Sources: CFPB, lending and borrowing with family and friends; Boston College Center for Retirement Research, “Kids’ College Trumps Parents’ Retirement”; IRS gift-tax FAQs. Family scenes and dollar examples are illustrative, not reports about a particular family. General education, not individualized financial, tax or legal advice. Cover: AI-created conceptual illustration.
Share a line
Pass this one along
Pick a line, save the card, and send it to whoever needs to read it.
Your next step
Questions about your own retirement?
Talk it through with a licensed advisor on our team. Ask your questions, get straight answers, and leave with a clear place to start. No cost, no obligation, nothing sold on the call.
Run your own numbers
The Let’s Start tool
Prefer to try it yourself first? It’s a calculator that sets a retirement income target and shows how much savings could support it.
Open the Let’s Start →Advisory and insurance services are provided by licensed professionals; availability varies by state.
The Conversation
No comments yet. Tell us where we got it right — or where we're dead wrong.
Comments are for members — it keeps the spam out and the conversation honest.
Create a free account