
Your Retirement Plan Might Be Fantasyland. Here Are 7 Missing Pieces.
The castle is lovely. The moat is not a cash reserve. Before you retire on a beautiful projection, check the seven pieces that turn a dream into a plan.
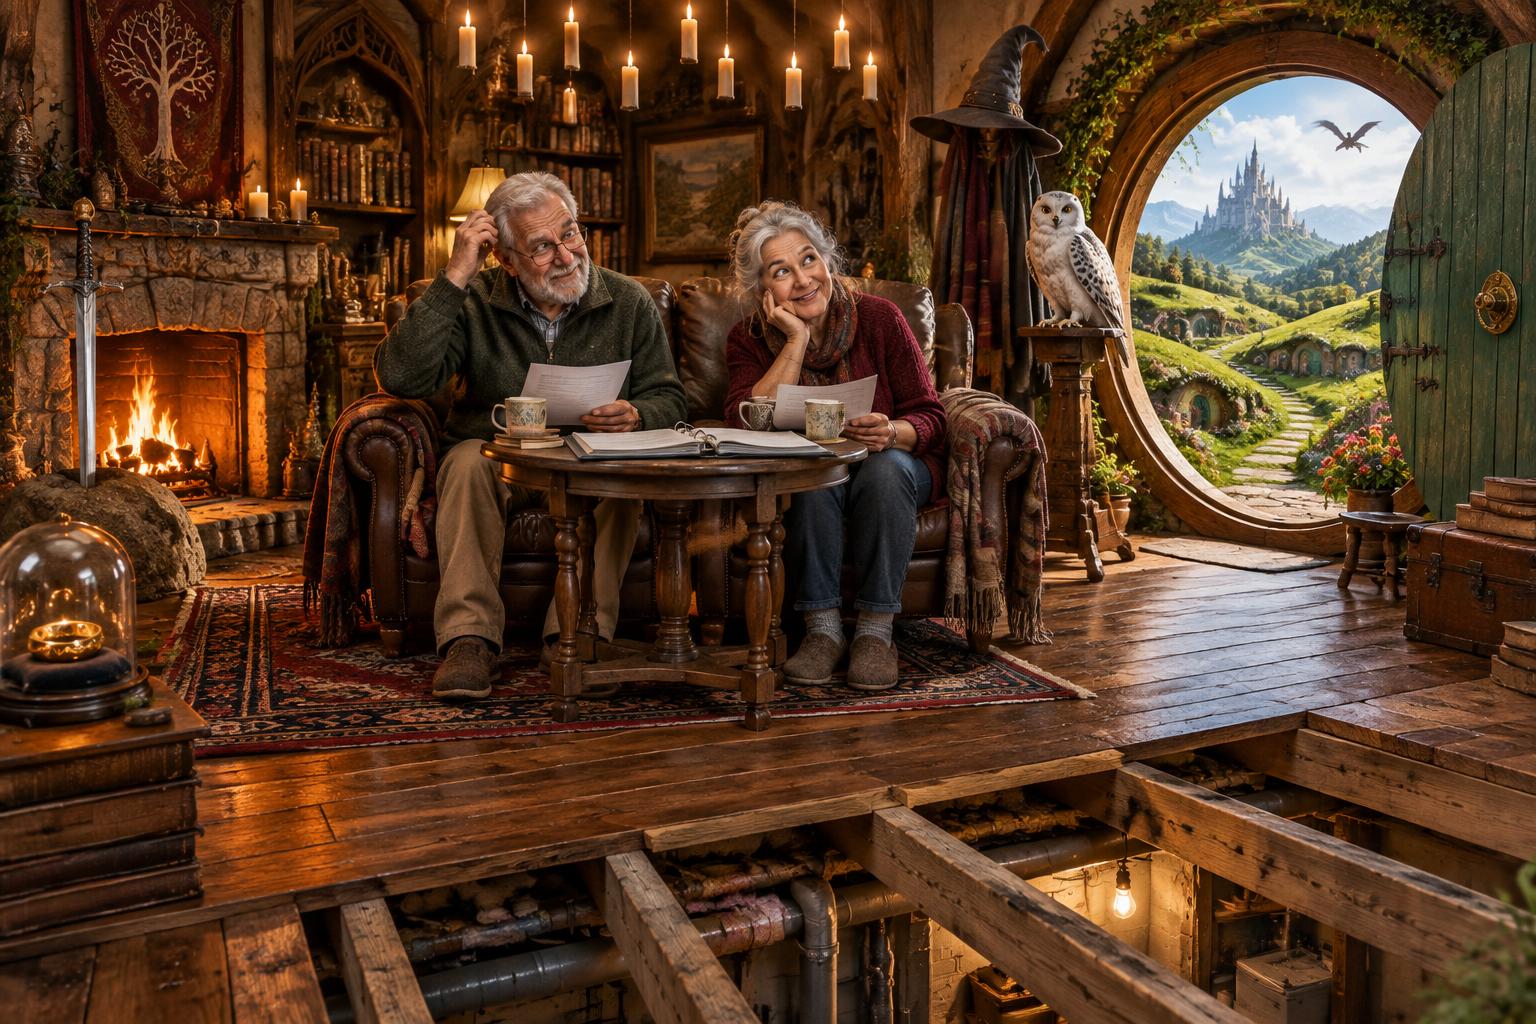
You have the retirement date. The travel list. The house with the good view. Maybe even a spreadsheet that stays reassuringly green all the way to age 95.
Lovely.
But if the numbers work only when markets cooperate, nobody needs care, taxes behave and both of you live forever, you may not have a retirement plan.
You may have a very expensive fantasy novel.
There is nothing wrong with dreaming about your second act. The problem is mistaking the scenery for the foundation. A castle looks magnificent right up until you discover that somebody forgot the floor.
So let’s leave the enchanted forest for a minute. Here are seven pieces that deserve a place in the plan before you hang up your work badge.
Cover: AI-created editorial fantasy illustration. The couple and setting are fictional; the magical decor is a playful metaphor, not an affiliation with any film franchise.
1. A Real Spending Number — Not “We’ll Need Less”
In Fantasyland, retirement automatically makes life cheaper.
In your actual house, the property-tax bill does not care that you stopped working. Neither does the roof, the car or the grandchild getting married.
Some expenses may fall. Others may rise. Neither direction belongs in the plan simply because it sounds plausible.
Start with your actual bank and credit-card records. Separate essential living costs, flexible enjoyment spending and irregular expenses. A replacement furnace is irregular. It is not imaginary.
Then add the commitments you tend to leave out: family support, home maintenance, travel, insurance and taxes.
The question: Can you show what your household needs to spend in a normal year, and what a lumpy year could cost?
2. A Retirement Paycheck — With Start Dates Attached
“We have a million dollars” describes a balance. It does not describe next Tuesday’s grocery money.
A workable plan shows where cash will come from, when each source begins and which expenses it is expected to cover.
List Social Security estimates, pension choices, other reliable income and the amount you expect investments to supply. Distinguish a contractual promise from an optimistic estimate. If an insurance product is involved, understand its conditions, costs and the insurer behind the promise.
Social Security timing belongs in this conversation. Starting sooner versus later changes the monthly benefit; the choice should reflect your circumstances, not an internet slogan. Review your own record and estimates through Social Security. [1]
If you stop working before a benefit begins, the gap needs a funding source. “We’ll figure it out” is not one.
The question: Where does the money come from during the first year, the transition years and the later years?
3. An After-Tax Plan — Because the Balance Is Not All Spendable
Fantasyland has a delightful tax code: there isn’t one.
Here, pension payments and IRA distributions can be taxable, depending on the account, contributions and applicable rules. Qualified Roth distributions are treated differently. Social Security benefits can also be partly taxable. [2] [3] [4]
That does not mean every retirement dollar gets the same treatment. It means the account you draw from matters.
A spending goal and a withdrawal amount are not automatically the same number. Review federal and state taxes, account types and the timing of withdrawals with a qualified tax professional.
The question: How much reaches your checking account after taxes — not just how much leaves the portfolio?
4. A Bad-Market Playbook — Not One Beautiful Average
A projection that assumes the same return every year is wonderfully well-behaved. Markets are not.
When you are withdrawing money, the order of returns matters. Selling investments during a decline can leave fewer dollars participating in a later recovery.
Here is a deliberately simplified illustration, not a forecast: start with $100,000 and withdraw $10,000 at the beginning of each year. A 20% decline followed by a 25% gain leaves $77,500 after two years. Reverse those returns and you finish with $82,000. Same two market returns. Same withdrawals. Different ending balance. Taxes, fees and inflation are excluded.
No, this does not prove a particular investment or withdrawal rate is right for you. It shows why “the average should be fine” is an incomplete answer.
Discuss how essential expenses would be funded through a rough stretch, what spending could change and when you would review the plan. Cash reserves have trade-offs too; their size should fit your situation, not a magic number.
For the bigger withdrawal debate, read our Ramsey–Pfau showdown.
The question: What would you do if the first years of retirement were disappointing ones?
5. A Healthcare and Care Plan — Those Are Two Different Things
“Medicare will handle it” is doing an astonishing amount of work in some retirement plans.
If you retire before Medicare eligibility and lose employer coverage, you need to investigate the bridge. HealthCare.gov explains Marketplace options for early retirees, including how eligibility for savings depends on income and household size. [5]
Once you have Medicare, healthcare still is not automatically free. Premiums, deductibles and other out-of-pocket costs depend on the coverage and services you use. [6]
And long-term help with daily activities is a separate issue. Medicare generally does not pay for non-medical long-term, or custodial, care. That is different from qualifying covered skilled care. Medicaid eligibility and private coverage have their own rules. [7]
Talk about where care could happen, who could realistically help and how you would pay. Do not quietly assign your daughter the role of full-time caregiver because she lives closest.
The question: Have you planned for health coverage and for possible ongoing assistance — separately?
6. A Longer-Life and One-Spouse Test
In fantasy films, characters occasionally get several lifetimes. In retirement, you just need the money to support the one you actually get — however long it turns out to be.
Run more than one time horizon. Test higher living costs as well. A fixed payment may keep its dollar amount without keeping its buying power.
For couples, also run the plan for each person living alone. Ask what happens to Social Security, pension income, taxes, housing and care costs. Do not assume that two checks continue unchanged, or that losing one person cuts every bill in half.
A survivor also needs access to the information, not just a reassuring phrase about where it is stored. The CFPB has resources on later-life finances and planning for financial incapacity. [8]
The question: Does the plan still work if one of you lives much longer — and can that person actually operate it?
7. Written Decisions — and Someone Who Can Find Them
The final missing piece is often not money. It is instructions.
Review beneficiary designations, estate documents, financial powers of attorney and healthcare directives with the appropriate professionals. The right documents and their effects depend on your circumstances and state law.
Keep an accessible inventory of accounts, insurance, key contacts and where important documents are held. Arrange secure access rather than casually sharing passwords or scattering sensitive information.
Then discuss the family commitments that could change the math: ongoing support, loans, gifts and the home everybody assumes somebody will inherit.
If that conversation feels overdue, start with Your Will Is Done. Your Family Isn’t. and The Bank of Mom and Dad Needs a Closing Time.
The question: If you could not manage things tomorrow, would the right person know what to do — and have the authority to do it?
The Fantasyland Test: Which Answer Is Still “Probably”?
You do not need seven perfect answers by dinner. You do need to stop treating seven assumptions as seven answers.
- We probably will spend less.
- The investments probably will earn enough.
- Medicare probably will cover it.
- The kids probably will understand.
- My spouse probably knows where everything is.
“Probably” is not a funding source.
Pick the biggest blank. Put it on paper. Bring it to the person qualified to help you resolve it. Then review the plan when your circumstances change, rather than treating the first version as a lifetime permission slip.
The goal is not to abandon the beautiful retirement. It is to give it a floor.
Bring the Dream. Bring the Numbers.
Use the Second Act 360 Tool Chest’s “Let’s Start” tool to explore your retirement income target. Treat the result as a starting point, not a guarantee or a substitute for a full review.
Then join our Retirement Webinar: Setting the Stage for 2027 and bring the questions your spreadsheet has been politely avoiding.
Sources: [1] Social Security, Plan for retirement. [2] IRS, Topic 410: Pensions and annuities. [3] IRS, Individual Retirement Arrangements. [4] IRS, Topic 423: Social Security benefits. [5] HealthCare.gov, Health coverage for retirees. [6] Medicare.gov, Medicare costs. [7] Medicare.gov, Long-term care. [8] Consumer Financial Protection Bureau, Working with older adults. Official links appear beside the relevant discussion; rules and costs can change.
This article is general education, not individualized investment, tax, insurance or legal advice. Illustrations are not forecasts. Consult appropriately qualified professionals about your own situation.
Share a line
Pass this one along
Pick a line, save the card, and send it to whoever needs to read it.
Your next step
Questions about your own retirement?
Talk it through with a licensed advisor on our team. Ask your questions, get straight answers, and leave with a clear place to start. No cost, no obligation, nothing sold on the call.
Run your own numbers
The Let’s Start tool
Prefer to try it yourself first? It’s a calculator that sets a retirement income target and shows how much savings could support it.
Open the Let’s Start →Advisory and insurance services are provided by licensed professionals; availability varies by state.
The Conversation
No comments yet. Tell us where we got it right — or where we're dead wrong.
Comments are for members — it keeps the spam out and the conversation honest.
Create a free account